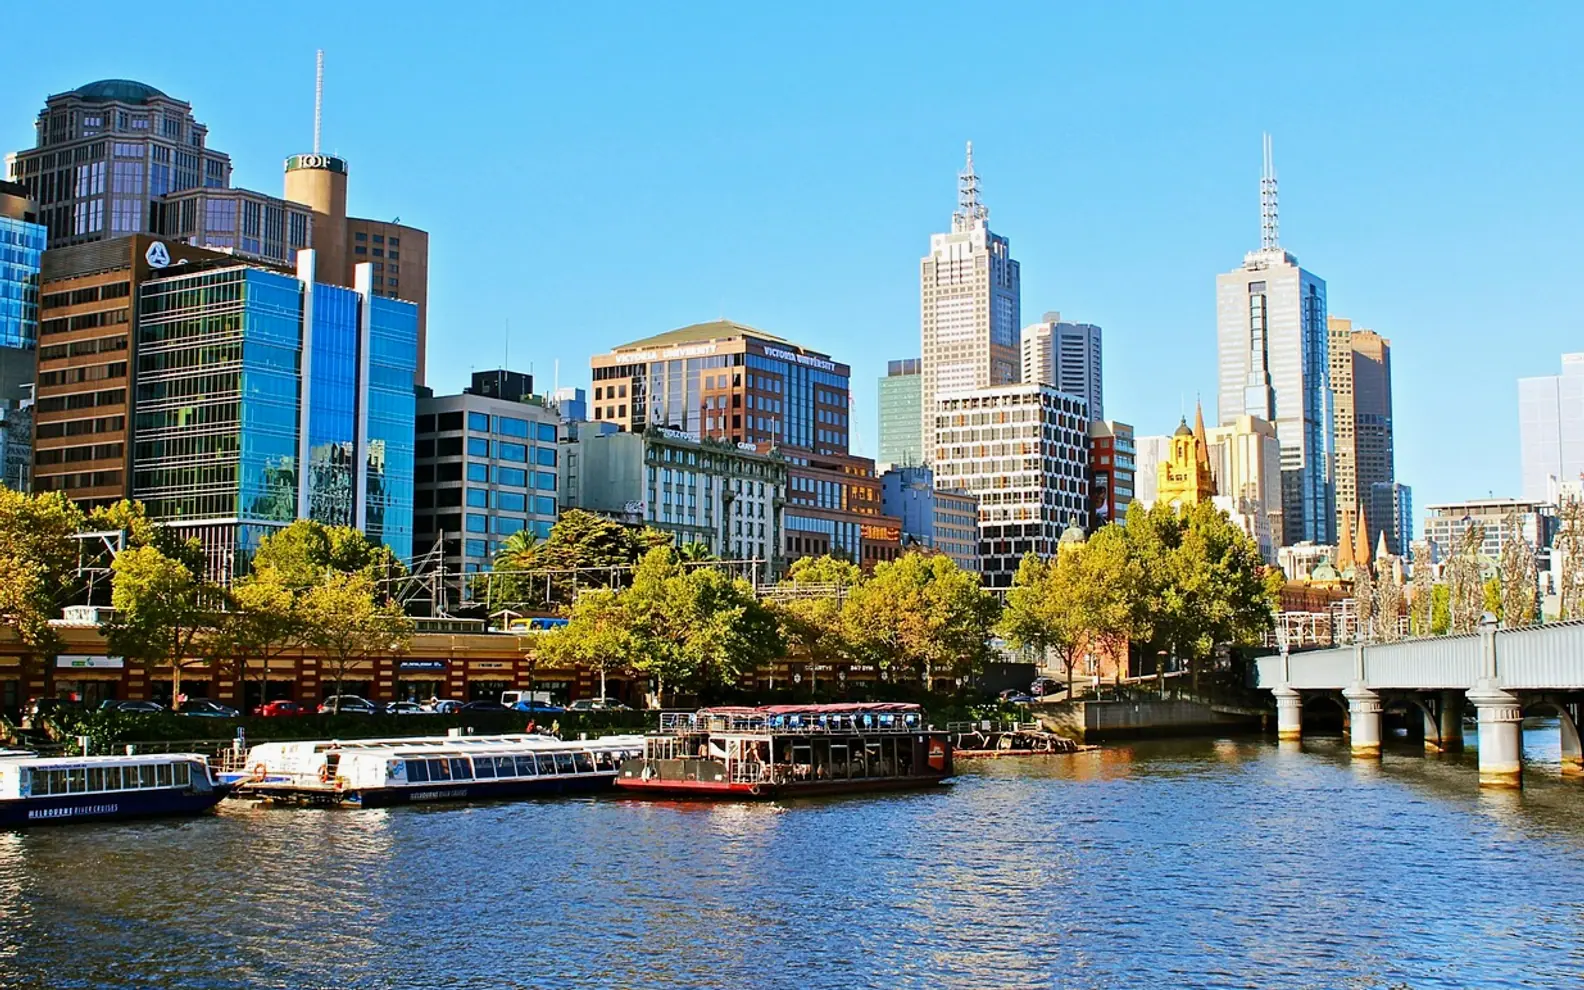
Mortgages in Melbourne: Why Using a Broker Is Always the Smart Choice
Buying property in Melbourne? See how a mortgage broker compares lenders, handles paperwork and keeps auction timelines on track, plus questions to ask first.
Saturday auctions, open inspections squeezed into lunch breaks, a deposit that took years to build: buying in Melbourne is demanding before the loan is even discussed. Then comes the lending side, with dozens of products that each have their own rates, fees, features and approval rules. It is no surprise that many buyers hand that part of the job to a mortgage broker.
What a broker actually does
A broker acts as the go-between for borrowers and lenders. The work usually covers:
- Understanding your income, expenses, deposit and goals.
- Comparing loans from a panel of lenders rather than a single bank.
- Explaining features such as offset accounts, redraw facilities and fixed or variable rates.
- Preparing and lodging the application, then following it through to settlement.
- Arranging pre-approval so you can bid or make offers with more confidence.
Australian law also places a best-interests duty on brokers, so their recommendations are meant to put the client's needs first.
Why it helps in a Melbourne market
The city's property mix is broad, from inner-city apartments and period terraces to new estates on the growth fringes. Lenders treat these differently, and their policies vary for first-home buyers, self-employed applicants and investors. A broker who works with these situations regularly knows which lenders are comfortable with a given property type or income structure, which can save a borrower from applying in the wrong place and starting again.
Timing matters too. When an auction is weeks away, a broker who knows how quickly different lenders process applications and what documents they will ask for can help keep things moving. Local firms like Blutin Finance Mortgage Broker focus on exactly this kind of support for Melbourne buyers, and you can see their location and read what past clients say on Google Maps before booking a first chat.
Questions worth raising early
- Which lenders do you work with, and what guides your recommendation?
- How are you paid, and will you tell me what commission you receive?
- Which features would suit my situation, and which might I not need?
- What will the loan cost over its life, including fees, not just the headline rate?
- How will you keep me updated during the application?
A good broker welcomes these questions and answers them in plain language.
The borrower still decides
A broker brings choice and saves time, but the loan remains a long-term commitment and the final call is yours. Because rates can climb during a long loan term as easily as they drop, work out whether the repayments would still fit your budget after an increase, and keep a buffer for unexpected costs such as repairs or a change in income. Read every loan document before signing, and if you are unsure how a product fits your wider finances, seek independent financial or legal advice.
Handled carefully, a broker relationship turns a stressful maze into a guided process, leaving you free to focus on finding the right home in the right suburb.
Across the sections
More from Real Estate
-
 No. 059 Real Estate
How a Comparative Market Analysis Can Unlock Your Property’s Potential
2 min -
 No. 051 International
Tips for Moving to Munich, Germany: A Practical Guide for a Smooth Relocation
3 min -
 No. 024 Real Estate
Getting the Numbers Right: How to Calculate Asphalt Tonnage with Accuracy
2 min