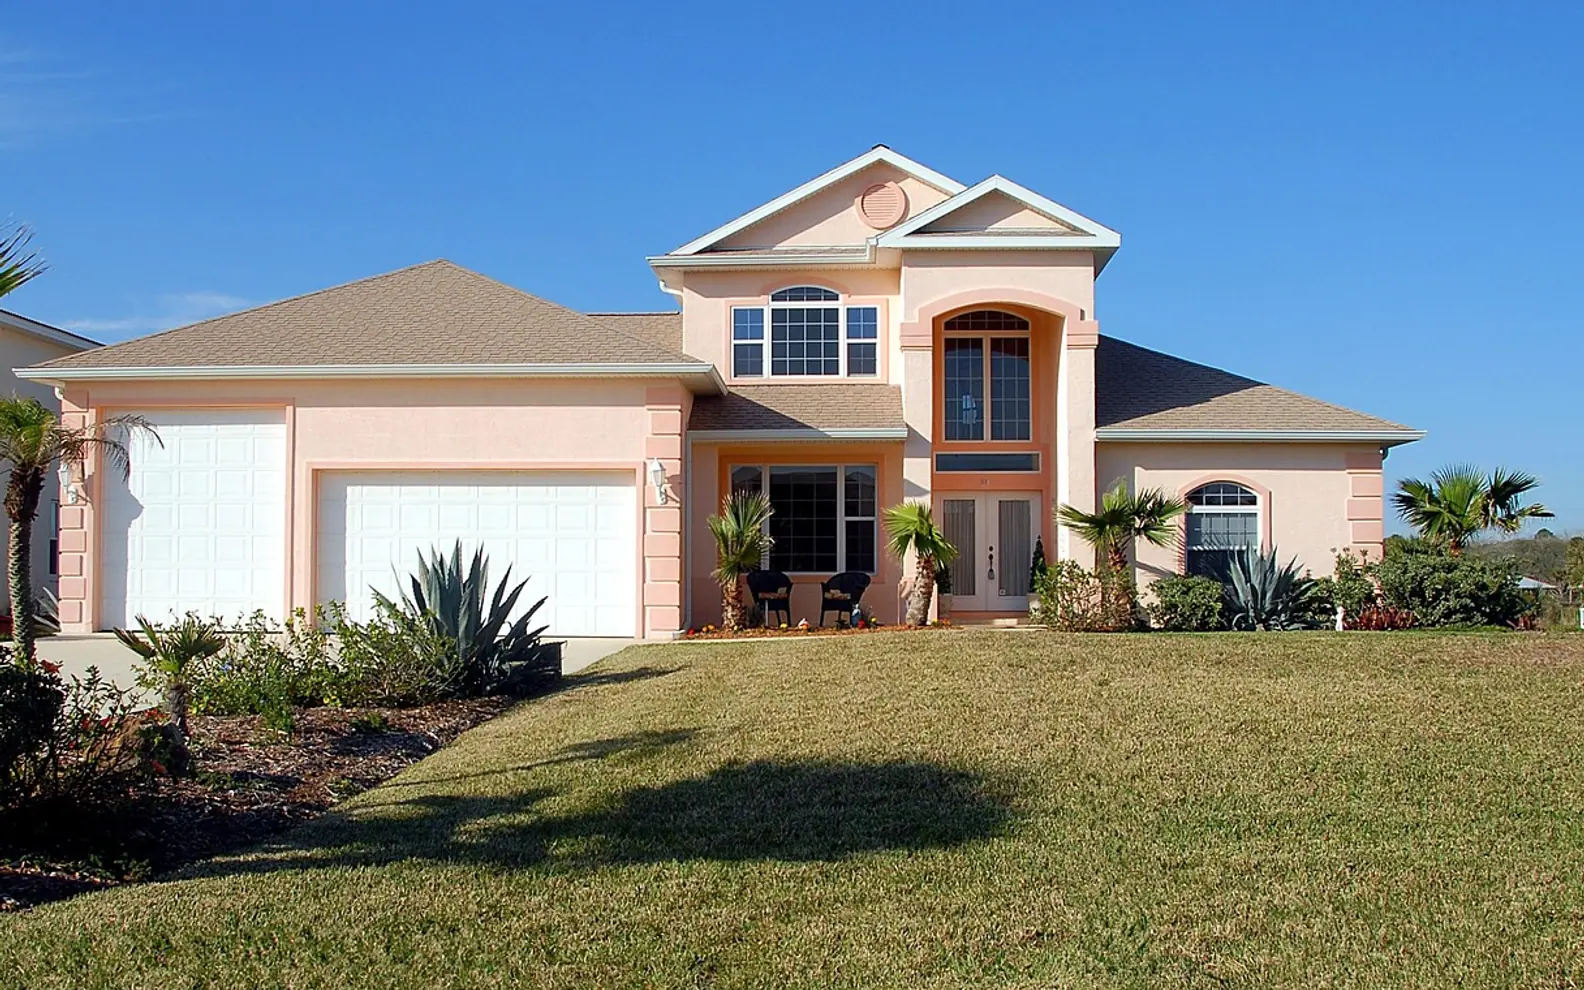
How a Comparative Market Analysis Can Unlock Your Property’s Potential
How a comparative market analysis uses nearby sales to estimate a home's value, which adjustments matter and how owners can put the results to use.
Ask three neighbours what a house on the street is worth and you will probably hear three different answers, each shaped by memory, hope or a headline about the national market. A comparative market analysis replaces that guesswork with evidence drawn from the immediate area, giving owners a grounded view of where their property stands.
Comparables: the heart of the analysis
A CMA looks at homes that resemble yours as closely as possible: similar size, age, layout, plot and condition, ideally in the same neighbourhood. It usually gathers three groups of properties:
- Closed sales, the clearest record of what buyers agreed to pay.
- Properties under contract, an early signal of the current direction.
- Active listings, which reveal the competition a seller would face today.
Listings that sat unsold or were withdrawn can be informative too, because they often show the price points buyers resisted.
Adjustments make the comparison fair
No two homes are identical, so the raw sale prices are adjusted. A comparable with an extra bathroom, a newer roof or a garage may be adjusted down to match a home without those features, while one needing repairs may be adjusted up. Location details matter as well: a busy road, a park view or a sought-after school catchment can shift value noticeably within a few streets. The skill of a CMA lies in making these adjustments consistently and explaining them clearly.
Putting the findings to work
Owners use a CMA in several ways. Sellers rely on it to choose a list price that draws viewings without leaving money on the table. Owners planning improvements can see which features nearby buyers seem to value, helping them decide between a kitchen update and a fresh coat of paint. People considering refinancing, settling an estate or dividing property after a separation sometimes use a CMA as an early reference point before more formal steps.
For homeowners who want a structured starting point, an online CMA report can pull together recent local sales and listings in one place, making it easier to review comparables and talk through pricing with an agent.
Limits worth keeping in mind
A CMA is an estimate, not a guarantee. It reflects market conditions at a specific moment, and those conditions can change as interest rates, inventory and buyer demand move. Nor is it the same as a formal appraisal; lenders usually ask for that separately, and it follows its own standards. Small markets with few recent sales can make comparables harder to find, which widens the range of reasonable values.
Getting the most from the numbers
- Share accurate details about upgrades, repairs and any known issues.
- Ask why each comparable was chosen and how it was adjusted.
- Look at the range of values, not just a single figure.
- Refresh the analysis if months pass before you act.
Property is usually a household's largest asset, and pricing decisions carry real financial consequences. Treat any analysis as one input among several, and get independent advice from a qualified agent, appraiser or financial adviser before making a major decision.
Across the sections
More from Real Estate
-
 No. 051 International
Tips for Moving to Munich, Germany: A Practical Guide for a Smooth Relocation
3 min -
 No. 047 Real Estate
Mortgages in Melbourne: Why Using a Broker Is Always the Smart Choice
2 min -
 No. 024 Real Estate
Getting the Numbers Right: How to Calculate Asphalt Tonnage with Accuracy
2 min